| AGENDA ITEM #: 19. DATE: 05/24/2021 AI #:114 |
 |
CITY COUNCIL ACTION REPORT
| SUBJECT: | ADOPTION OF FY2022 TENTATIVE BUDGET AND SETTING OF PUBLIC HEARING |
| STAFF PRESENTER(S): | Doug Sandstrom, Finance Director |
SUMMARY
Summary: Presentation and consideration of adoption of the FY2022 Tentative Budget in the amount of $568,473,400 for all funds.
The FY2022 Annual Budget provides for day-to-day operations, the first year of the five-year CIP, debt service, new ongoing and one-time supplemental budget additions, and carryovers from the FY2022 budget. This budget increases the authorized position count by 86.75 to 837.15 full-time equivalent (FTE) positions and includes the costs of the labor agreements with represented police and fire as well as all non-represented compensation and benefit changes.
Tentative Budget All Funds FY2022 - $568.5 million
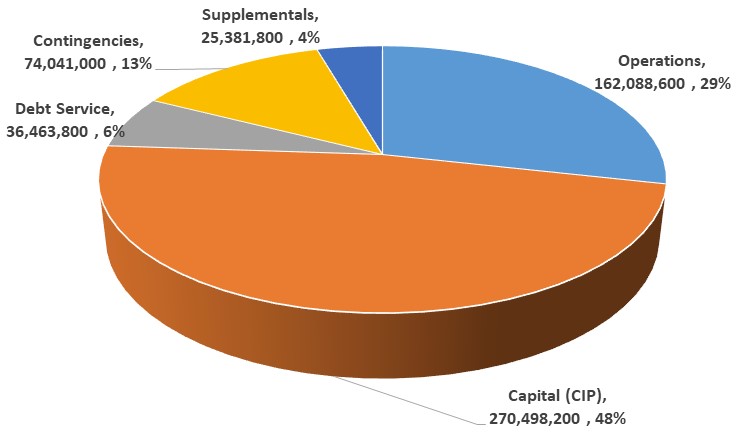
The Tentative Budget has increased $182.8 million over the recommended budget presented in April, the following sections explain all changes.
Resource Changes:
The Beginning Balance across all funds increases as a result of the inclusion of FY2021 carryovers. These carryovers represent projects and one-time supplementals that are currently budgeted, but will not be finalized by the end of the fiscal year. The increase in the FY2022 beginning balance results from an equal decrease to FY2021 estimated expenditures and a corresponding increase to FY2022 budgeted expenditures. In addition to fund balance changes there is $54,900 decrease in anticipated grant revenue and an increase in $205,000 associated with the planned contribution from the teams for the ballpark netting project.
Operating budget changes include:
Capital project changes include:
Contingency changes include:
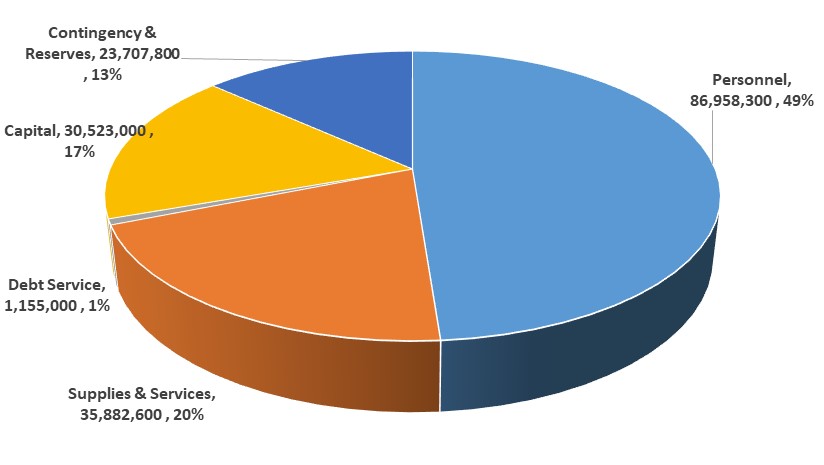
The FY2022 General Fund Budget, which is the primarily tax-supported portion of the citywide budget, is $178.2 million. As the operating fund of the City the majority of employees are funded out of the general fund and that is reflected by the fact that 49% of general fund expenditures are personnel related. Our heavy investment in infrastructure is also reflected in the general fund as 17% of the budget is for CIP projects. The general fund includes our 15% Policy Reserves which are included in the Contingency & Reserve category at $19.0 million. The majority of the remaining contingencies are to fund future years of the CIP.
General Fund FY2022 Tentative Budget - $178.2 million
The FY2022 Annual Budget provides for day-to-day operations, the first year of the five-year CIP, debt service, new ongoing and one-time supplemental budget additions, and carryovers from the FY2022 budget. This budget increases the authorized position count by 86.75 to 837.15 full-time equivalent (FTE) positions and includes the costs of the labor agreements with represented police and fire as well as all non-represented compensation and benefit changes.
Tentative Budget All Funds FY2022 - $568.5 million
The Tentative Budget has increased $182.8 million over the recommended budget presented in April, the following sections explain all changes.
Resource Changes:
The Beginning Balance across all funds increases as a result of the inclusion of FY2021 carryovers. These carryovers represent projects and one-time supplementals that are currently budgeted, but will not be finalized by the end of the fiscal year. The increase in the FY2022 beginning balance results from an equal decrease to FY2021 estimated expenditures and a corresponding increase to FY2022 budgeted expenditures. In addition to fund balance changes there is $54,900 decrease in anticipated grant revenue and an increase in $205,000 associated with the planned contribution from the teams for the ballpark netting project.
Operating budget changes include:
- $179,400 reduction across all departments to reconcile actual workers compensation rates with those used in the development of the recommended budget
- $4.9 million increase due to the inclusion of Non-CIP carryovers. A complete list of carryovers is included with this item.
Capital project changes include:
- $744,000 reduction in the water fund attributable to the erroneous programming of Project 60075 Amiad Filter replacement in both FY2022 and FY2023. This project remains budgeted as planned in FY2023
- $157.9 million increase due to the inclusion of CIP carryovers. A complete list of carryovers is included with this item.
Contingency changes include:
- CIP Reserves - These funds are planned to fund future years of the adopted CIP. Any use of CIP reserve requires City Council authorization.
- $4.0 million addition of General Fund CIP Reserves.
- $14.5 million addition of CIP Reserves in various restricted funds.
- Contingencies – Various restricted funds with an existing fund balance have had all available funds budgeted for use by adding a contingency line-item within the fund. Any use of Contingencies requires City Council authorization.
- Park & Ride Fund - $1.1 million
- Impound Fund - $199,000
- Court Enhancement Fund - $233,100
- Fill the Gap fund - $33,600
- Judicial Collection Enhancement Fund - $124,500
- Officer Safety Equipment Fund - $57,300
The FY2022 General Fund Budget, which is the primarily tax-supported portion of the citywide budget, is $178.2 million. As the operating fund of the City the majority of employees are funded out of the general fund and that is reflected by the fact that 49% of general fund expenditures are personnel related. Our heavy investment in infrastructure is also reflected in the general fund as 17% of the budget is for CIP projects. The general fund includes our 15% Policy Reserves which are included in the Contingency & Reserve category at $19.0 million. The majority of the remaining contingencies are to fund future years of the CIP.
General Fund FY2022 Tentative Budget - $178.2 million
Recommendation
ADOPT RESOLUTION NO. 2021-2160 ADOPTING THE FISCAL YEAR 2021-2022 ESTIMATES OF REVENUES AND EXPENSES FOR THE CITY OF GOODYEAR, INCLUDING ESTIMATED PROPERTY TAX LEVY AND PROPERTY TAX RATES, AS THE TENTATIVE BUDGET FOR FISCAL YEAR BEGINNING JULY 1, 2021 AND ENDING JUNE 30, 2022; SETTING FORTH THE RECEIPTS AND THE AMOUNTS ESTIMATED AS COLLECTIBLE FOR THE PREVIOUS FISCAL YEAR; THE AMOUNT PROPOSED TO BE RAISED BY DIRECT PROPERTY TAXATION FOR THE VARIOUS PURPOSES; GIVING NOTICE OF THE TIME FOR HEARING TAXPAYERS; FOR ADOPTION OF BUDGET AND SETTING THE TAX LEVIES. (Doug Sandstrom, Finance Director)
FISCAL IMPACT
This is the first official step in adopting the FY2022 budget. Adoption of the tentative budget sets the expenditure limitation amount for FY2022 and authorizes expenditure of funds in FY2022. No sales tax rate changes are included in this budget, primary property taxes are at the maximum levy consistent with financial policy, and the secondary property tax levy is set so that combined the total property tax rate remains under $1.74 per $100 of assessed valuation. Further, no other rate or fee changes are included in the budget. However, separate rate and fee studies are in progress for citywide user fees including permit and planning fees. Enterprise fund rate changes occur in January and approved rate increases are included in the FY2022 tentative budget.
BACKGROUND AND PREVIOUS ACTIONS
The FY2022 budget process began in the fall with departments submitting their initial list of new capital project requests as part of the CIP budget process that stretched through January. In October, departments began preparing base budget estimates and updating existing CIP project costs and timelines if needed and by December had also submitted supplemental budget addition requests. All of these estimates and requests are reviewed by Budget and Research and with the executive team. In the case of capital projects; Engineering Project Management, Information Technology, and Procurement were also involved in reviews.
In November and in early February, the Council provided insight into initial budget priorities in discussions held as part of a retreat and also at a council budget work session. Revenue policy was also a topic at that session with no planned changes to tax rates and slight adjustments to our financial policies.
The first formal step in this budget process with the City Council, was the presentation of the five-year General Fund forecast during a work session held on February 1, 2021.
On February 8, 2021, the City Council approved the financial and public safety pension policies. The two key changes in the financial policies was the introduction of a spending hierarchy from most restricted to least restricted and the increase from $5.1 million to $5.6 million, the portion of construction sales tax treated as ongoing revenue. This policy calls for annual review and the $5.6 million was based on the average of the lowest five-years in the prior ten-years of General Fund construction sales tax collections. The public safety pension funding policies remained unchanged, but state statute requires annual Council approval including acceptance of the unfunded liabilities.
The City Manager presented a sustainable recommended budget on April 19, 2021 which focused on growth, continuing existing programs and services to a larger residential base, fair compensation for employees, meeting obligations, opening new capital facilities, and continuing the capital improvement program. The changes to that recommended budget are summarized in this report. To comply with state statute, the Council must adopt a tentative budget. Budget and Truth in Taxation publications will each appear twice in the newspaper per state requirements. The required public hearing for budget adoption, Truth In Taxation and Final Budget adoption will follow on June 7, 2021. The Property Tax Levy adoption will occur on June 21, 2021.
STAFF ANALYSIS
This budget was built from a framework of a continued strong local and national economies with city revenues that have fully recovered from the coronavirus pandemic. Though some uncertainties still exist, the rate of vaccinations and the presence of federal stimulus dollars are positively impacting spending patterns by consumers and businesses. The budget framework remains one of maintaining current programs and services, adding depth to support services, addressing the highest priorities expressed by City Council, compensating employees fairly, providing capacity to absorb revenue losses or cost increases, and continuing the capital improvement program given both the needs of the organization and the benefits that derive to the local economy from such projects. The FY2022 tentative budget complies with all financial policies including General Fund ongoing resources exceeding the ongoing uses. Further, the operating cost set-aside, which is used to step the General Fund budget into future capital project operating costs by using ongoing revenues equal to the set-aside for one-time purposes is at $1.0 million.